Two inflation reports, two days, opposite reactions. The calm one knocked stocks down. The hot one sent them up almost 1%. If that feels backwards, you read it right.
What the two reports actually measure
PPI is what businesses charge each other. CPI is what you pay. Same inflation, measured at two points in the same pipe.
| Report | August | Past 12 months |
|---|---|---|
| PPI, wholesale prices | 0.4% | 5.4% |
| CPI, consumer prices | 0.4% | 3.4% |
Thursday's PPI looked fine on the surface. Up 0.4% for the month, right where forecasts sat. Underneath, it was almost all fuel. Goods prices rose 1.1% while services barely moved at 0.1%, and the BLS put over three-fourths of that goods increase down to energy. Diesel by itself rose 24.1%. Diesel moves food, lumber and packages, so that number tends to turn up later inside other people's costs.
Friday's CPI matched expectations on the headline: 0.4% for the month, 3.4% over the year. The number that moved things was core inflation, which drops food and energy. It rose 0.3% against a 0.2% consensus. Gasoline was up 3.9% on the month, with the national average now around $4.28 a gallon.
The market was trading oil
Thursday the S&P 500 fell 0.58%, a fourth straight down day. Crude closed at $102.48, up 6.7% and the highest since May. The 10-year Treasury yield went above 4.95%, last seen in 2023.
Friday, crude settled at $100.05, down 2.4%, and everything turned green. The S&P 500 rose about 0.9%, the Dow added 509 points, and all eleven sectors finished higher. The 10-year ended at 4.96%, near enough to where it opened.
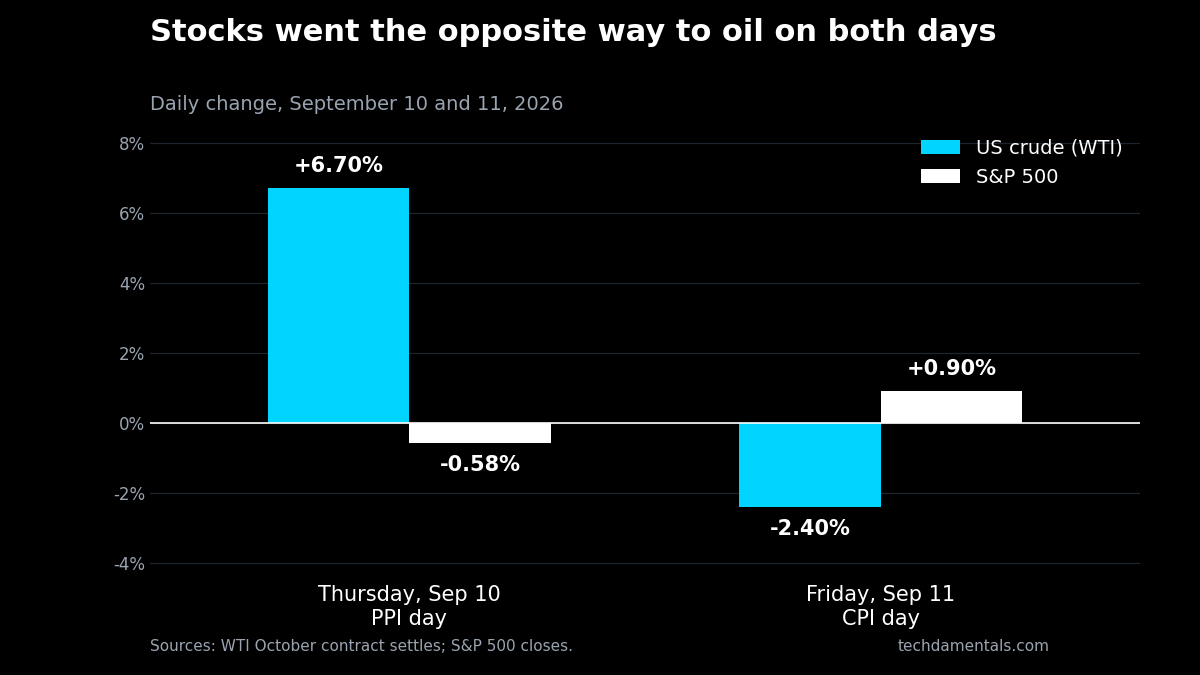
So the cleanest reading is that stocks were trading crude, and the inflation reports were background noise. Call it a reading, not a fact. Friday's move in oil was small next to the week's, which still left crude up 9.4% over five sessions, and a market that has fallen four days running will bounce on thin excuses.
What is already priced in for Wednesday
Rates have sat between 3.50% and 3.75% all year. A quarter-point increase puts them between 3.75% and 4.00%. In two days, futures went from something near a coin flip to something close to settled.
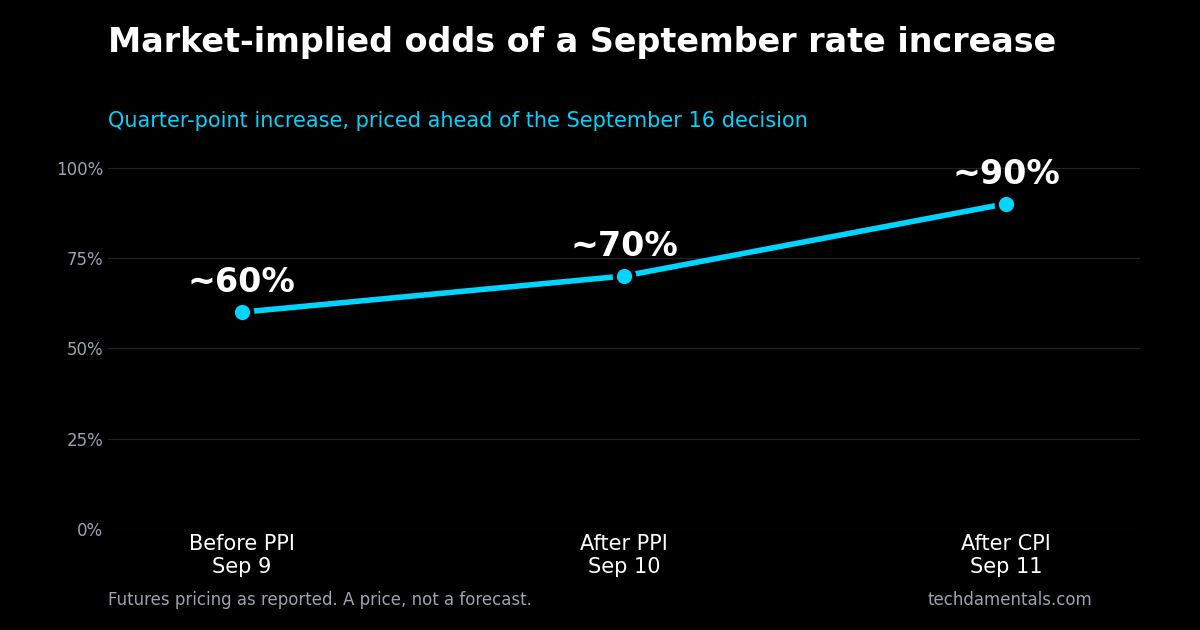
That is not a forecast. It is a price, and prices are wrong often enough to matter.
Wednesday afternoon brings the decision and a fresh set of quarterly projections. June's had the median rate at 3.8% by year end, so they may say more about the next six months than the decision does.
You can already see where higher rates land first. It is less about a sector than a balance sheet. Companies that borrow at floating rates, that have debt maturing soon, or that are not yet profitable feel a rate move immediately. The Russell 2000 is full of all three, and it finished Friday 10.9% below its record high, down more than 7% this month, the first major index in correction this year. The other pressure point is any company whose value sits in profits that arrive years from now, because a higher yield discounts those harder. That is why semiconductors led Thursday's decline while the 10-year was climbing. Energy was the only corner of the market that had a good week.
What this does not tell you
Close to 90% is not certainty. Roughly one time in ten, it goes the other way. Nothing in that price tells you what happens after one increase, which is the part that matters if you hold anything longer than a week. And underneath all of it sits oil, moving on a war rather than on policy. That can turn in a single morning, either direction.
A week like this is a reminder that most of what moved your positions had nothing to do with the companies. Oil moved, yields moved, and prices followed. Techdamentals works the other direction. It values a company off its own cash flow, debt and growth, shows every input it used, and when its four methods land far apart it says so on the page instead of averaging the disagreement away.